Fraud preventionStop payment fraud at the source
Payhawk verifies business payments, corporate cards, expenses, and invoices, so fraud and expensive mistakes are stopped before they cost you.


Prevention built into every payment
Fraud rarely looks like fraud. A supplier changes bank details, a fictitious invoice arrives, an expense claim never happened, a card is used where it should not be. With 76% of organisations targeted by payments fraud last year, Payhawk is built to catch each one before money moves.
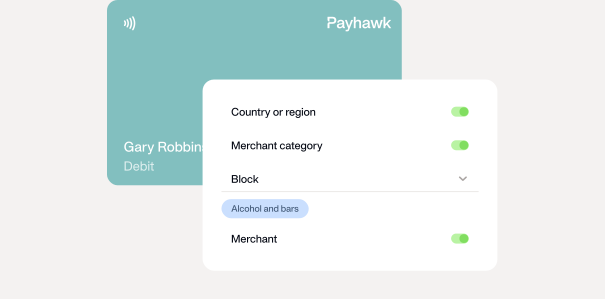
You control where each card can be used, by merchant, category, country, time, and limit. Card payments are auto rejected based on your spend controls
Duplicate invoices and expense claims are flagged automatically across amount, supplier, date, and document number. Where a purchase order exists, three-way matching confirms the goods arrived before the invoice is paid.

Every payee is checked on EUR and GBP transfers, whether you are paying a supplier or reimbursing an employee. A name that does not match the account is flagged before you pay.
We monitor card transactions and bank payments, so suspicious activity is caught and acted on fast, before it becomes a problem.
Stronger control for sensitive changes
Reduce risk with tighter access, dual approval, and a clear record of every change.
Require a second approver for supplier detail changes, internal fund transfers, and workflow updates. Sensitive changes take effect only after a second person approves.
Keep payment confirmation and authorisation with different people. Control exactly who can edit supplier bank details.
Get email alerts for new payees and permission updates. Four-eyes approval logs show the before-and-after values for every request.
The full payment fraud-prevention toolkit

Payee verification
Names on new or changed bank details are checked against the destination account on EUR and GBP payments, and mismatches are flagged before the transfer sends.

Duplicate detection and matching
Repeat invoices and claims are flagged across amount, supplier, date, and document number. Where a purchase order exists, three-way matching confirms the goods arrived before payment.

Granular corporate card controls
Set each card by merchant, category, country, time, and limit. Cardholders cannot raise their own limits.

3-D Secure authentication
Online card payments above a threshold prompt the cardholder to confirm in the app, so a stolen number alone is not enough.

Real-time monitoring
Bank payments get a payee-name check and sanctions screening, with monitoring for unusual activity. Card activity is monitored too, and a suspicious transaction can be declined or the card blocked.

Approval workflows
Route payments, invoices, and expenses through configurable approvals, and limit who can edit supplier bank details to a named few, so sensitive changes need more than one person.

Segregation of duties
Separate who confirms payment details from who authorizes a payment, and turn on dual authorization for updating supplier details or moving internal funds. Sensitive changes take effect only once a second person approves.

Full audit trail
Every action is logged, with alerts on new payees and permission changes and before-and-after values on every request, so you can see exactly what happened and evidence it for auditors.

Two-factor authentication
An extra identity check at login keeps a stolen password alone from reaching your company's funds.
Real finance teams. Real results


“The OCR flags any duplicate invoices and populates the fields, so it’s like the four eyes principle in action.”
Nadia Vanuytrecht


"This is a convenient, paperless, and totally secure process. If needed, you can freeze the card in a minute. Finance managers can administer limits and access to all expenses in real-time.”
Polina Kasaboneva, CFO


"With the tool we used before, we felt blind about certain information. I didn't know where to make adjustments and couldn't find things out fast enough. Now, with Payhawk, we can maintain visibility and control over spend, even as the number of receipts and invoices multiplies. And Payhawk's traceability empowers us to invest our cash where it will generate the greatest profitability.”
Adrià Vázquez, CFO
Discover enterprise power, without enterprise complexity
Manage employee expenses alongside all your other company spend. With Payhawk, you get complete control over your policies, workflows, and payments in a single platform.

Smart cards with built-in control

Review and repay employee expenses

Automate invoice processing

Fully digitised employee spend tracking, expense reports with custom approvals and direct reimbursement to employee bank accounts. link

Multiply your team's capacity with a suit of Al Agents. Handling finance tasks with precision, they ensure your team spends less time on routine work.
Unlock a new level of team productivity with automated payables
FAQs
Payhawk builds prevention into every payment, card, expense, and invoice. It verifies payees before a transfer, catches duplicate and fictitious invoices, flags fraudulent expense claims, applies granular controls to every card, and monitors card and bank payments, so fraud can be stopped before money leaves the business.
This is the classic vendor impersonation and bank-detail-change fraud. Payhawk checks the payee name against the destination account, and mismatches are flagged before a payment is sent, with a first-time vendor warning on new suppliers. You can control who is allowed to edit supplier bank details, and sensitive changes require a second approver, so a single person cannot redirect funds alone.
Duplicate detection flags a repeat across amount, supplier, date, and document number. Three-way matching stops a fictitious invoice that has no purchase order or delivery behind it, and a first-time-vendor warning adds a check before any new supplier is paid.
Payhawk layers card network, processor, and 3-D Secure checks with monitoring that can flag a suspicious transaction for review, decline it, or block the card.
Duplicate expense claims are flagged across amount, supplier, date, and document number, and the reviewer is alerted if a flagged field is edited after submission. Receipts are matched to each expense, approval reviews catch anything out of policy, and cards can auto-block when expenses are repeatedly submitted late.
Your funds are safeguarded with J.P. Morgan and other regulated institutions. Payhawk is a regulated electronic money institution in the UK and EEA and holds PCI DSS Level 1, SOC 1 and SOC 2 Type 2, and ISO 27001 certifications, with card payments on Visa Principal Member rails and 3-D Secure authentication.
Spend control keeps legitimate spend on policy. Fraud prevention stops illegitimate spend from ever leaving the business. Payhawk does both, but they solve different problems: policy compliance versus verified, protected payments.
Business card fraud causes direct financial loss, plus the admin burden of disputing transactions with the bank afterwards. Granular controls, approval-gated limits, and real-time monitoring reduce both the loss and the clean-up.
Payhawk syncs with the ERP and accounting software you already run, so fraud prevention layers onto your stack rather than replacing it. Your funds stay safeguarded with J.P. Morgan, so moving spend onto Payhawk does not mean leaving that protection behind.


