
How to choose the best international payment system


Your finance team doesn’t have to live in spreadsheets, bank portals, and emails to manage international vendor payments. This guide teaches you how to pay overseas vendors with more control and less effort. Learn how to choose between international payment systems to reduce admin, cut FX surprises, and drive growth.
- What a good international payment system does for Finance
- The rails an international payment system should support
- Evaluating international payment systems: Five decision criteria
- Bank vs fintech: Which option is best for your business?
- What to look for in an international payment provider
- Best international payment systems for paying suppliers
- Common mistakes when choosing an international payment system
- Is your international payment setup ready to scale?
- Choose a system that gives control, not just speed
By submitting this form, you agree to receive emails about our products and services per our Privacy Policy.
Your setup for paying overseas suppliers determines FX costs, settlement speed, and the control Finance has. Here’s where an international payment system comes in: the platform and rails your business uses to pay suppliers, staff, and other entities across currencies and countries.
A platform for international vendor payments goes far beyond triggering a bank transfer. Good international payment systems hold multiple currencies, select suitable rails, enforce approvals, and reconcile at every step. You might access one through your existing bank, a fintech platform, a money transfer specialist, or a combination of these. You decide who approves payments, how FX applies, and how accounts payable (AP) data reaches your ERP.
Picture this. You’ve just wrapped up a bumper quarter with climbing sales and a growing product catalog. But your company’s international payment systems tell a different story.
Using multiple solutions without a single audit trail creates admin, bottlenecks, and profit leaks. You see FX fees and intermediary costs after clearance. By then it’s too late to react. Each solution for international supplier payments offers varying levels of transparency in status and ERP syncing, obscuring actual spend.
These issues remain common. Cross-border payments can still take several days and cost up to 10 times more than a domestic payment, according to the Bank of England. In this guide, you’ll uncover what a good international payment system does and why the choice matters. You’ll also learn which rails it should support, how to compare models, and choose the best option.
One platform for supplier payments, FX, and approvals
What a good international payment system does for Finance
A payment platform is the control room for your international vendor payments. It shapes workflows, from FX decisions to data quality. A strong setup gives you control, faster payments, and fewer surprises. A good platform should:
- Hold multiple currencies to pay in the invoice’s currency and avoid double conversion
- Route each payment through the cheapest route, e.g., local rails or SEPA (Single Euro Payments Area) and ACH (Automated Clearing House)
- Make FX rates and fees visible before approval so budget owners can see actual costs
- Enforce approval before money moves, keeping finance in control of every payment
- Provide clear multi-entity management data on one dashboard for quick decision-making
- Sync each payment with its invoice, approval, and live status via ERP and accounting integrations
The rails an international payment system should support
Global money never moves in a straight line. It jumps rails, crosses borders, and can experience delays which affect delivery and cost. Knowing your options helps you choose the right rails. Let’s explore the main options.
SWIFT: Global reach, slower pace
Society for Worldwide Interbank Financial Telecommunication (SWIFT) is the backbone of cross-border banking. SWIFT moves messages between banks, not the money. Banks typically charge a flat fee per SWIFT transfer and add a 1–3% FX markup, and settlement usually takes three to five days.
SEPA: Euro-area transfers at low cost
SEPA handles euro-denominated transfers across participating countries. SEPA uses shared standards to move money quickly at low to no fees at many banks. With SEPA instant, payments arrive in seconds, making European supplier payouts feel almost domestic.
Local ACH and domestic rails: Fast in-country payouts
ACH in the US and domestic rails like Faster Payments in the UK move money within a single country. They offer near-domestic speed and low costs, especially on recurring invoices. Using local rails for cross-border setups often means pairing them with in-country accounts. Local accounts allow you to pay vendors from a local balance in their home market.
Digital wallets: Fast ad-hoc and contractor payouts
Digital wallets store payment details so users can pay from a phone, app, or website. They allow quick and easy payments, often with just the recipient’s email or phone number. Speed and reach make them popular. Digital wallets were forecast to account for around 54% of global e-commerce transaction value by 2026 (Worldpay Global Payments Report 2023).
Corporate cards: Instant spend with strong controls
A corporate card is a company payment card for authorized spend. They provide instant rails for SaaS subscriptions, travel, and card-accepting suppliers. Commercial and corporate card spending remains popular. Forecasts anticipate the market reaching around $88 billion by 2035. Corporate cards, including virtual options, play a key role in controlling and tracking business payments. Card spend converts at the Visa or Mastercard network rate on the settlement date, so the FX is transparent and close to mid-market (issue the card in the transaction currency to avoid an added conversion fee).
SEPA vs SWIFT
For multi-currency payments within Europe, SEPA gives lower fees and faster settlement. SWIFT is best for global payments outside of Europe where you need wider currency coverage but can accept higher cost and slower timing. For example, your team could pay a supplier in Germany via SEPA to keep fees low. SWIFT gives them access to corridors and currencies that SEPA doesn’t cover, like the US and the dollar.
See supplier payments move on the right rail

Evaluating international payment systems: Five decision criteria
When comparing international payment systems, you’re deciding the costs, speed, controls and integration that’ll shape your company’s profitability and growth. It’s critical to know how cross-border payments work. There are five core criteria to evaluate cross-border systems. Let’s break them down.
1. Cost and FX transparency
Headline FX rates alone are a trap. The total cost of multi-currency payments includes the sending fee, FX markup, and intermediary banking charges too. Ask: can my team see the full cost of each payment before approval? Also, check whether the system allows you to:
- Compare rails and providers for each corridor
- Decide whether to batch or pay individually
- Avoid routes that hide margin through spreads or bank fees
2. Rails coverage for your supplier countries
Payment rails are channels and methods for sending money. For example, say your suppliers are in the eurozone and Asia. Your team needs the right coverage for each region to ensure on-time international business payments. So, match rails to your business reality:
- Map supplier locations: List your vendors’ locations. Check which rails (e.g., SEPA, local ACH) your setup supports
- Align rails with volumes: Prioritize low-cost rails for high-volume corridors. Use faster, more expensive rails for high-priority transfers
- Review gaps regularly: When adding a new country, confirm current rails cover it. If not, decide whether to add a different rail or negotiate currency
3. Settlement speed
The Financial Stability Board's progress report to the G20 flags slow cross-border settlement as a barrier. The Bank of England also highlights that delays and opaque processes still create risk for global businesses. Many payments take days to clear. To ensure settlement windows match your needs:
- Review settlement times: Measure how long each rail takes to deliver
- Align speed with risk: Pick a system with flexible payment speeds. For example, it should offer fast rails for critical invoices and slower for regular ones
- Investigate provider reliability: Determine how often the solution meets on-time delivery targets. Favour options with consistent settlement times
4. Financial controls (approvals, invoice currency, audit trail)
Weak payment controls let duplicate disbursements, AP errors, and fraud eat into margins. Around 1.5% of disbursements are duplicate or erroneous payments, according to APQC benchmarking. Also, fraud examiners estimate that organizations lose about 5% of revenue to fraud each year. When comparing international payment systems, look for a platform that builds controls into every transaction.
Ensure it:
- Separates decision from payment: Check that budget owners can approve each invoice and monitor activity
- Supports payments in the relevant invoice currency: Ensure the platform has extensive currency options to avoid hidden FX fees from double conversions
- Keeps a complete audit trail: From approval to payment rails, the system should record all actions to make resolving issues easier
5. Integration (ERP sync and multi-entity)
Clean integrations turn uncertainty about how to pay overseas vendors into quick, repeatable workflows. Your team moves from data entry and tool switching to making strategic AP calls that boost cash flow. For example, your team can see all payments in a single view with Payhawk’s ERP and accounting integrations. They also get accurate data for financial close, accelerating processes.
Your payment solution should:
- Sync complete financial records: Payment data must flow into ERP and accounting systems, including invoices, FX, approvals, and statuses
- Support multi-entity management: Keep companies separate for reporting, but visible in one place for control and planning
- Reduce manual work and errors at close: Prioritize systems that use automation to improve invoice reconciliation
International payment system options
| System | Typical cost/FX | Speed | Rails coverage | Financial controls |
|---|---|---|---|---|
| Traditional bank | High (flat fee + typically 1–3% FX markup) | 3–5 days | SWIFT | Weak (manual approval, no ERP sync) |
| Money-transfer specialist | Low FX, per-transfer fee | 1–2 days | Local + SWIFT | Basic (simple payment approvals and accounting sync; limited AP workflow) |
| Card/wallet | Visa/Mastercard network rate + any card FX fee | Instant – 1 day | Card networks | Limited at scale |
| Single fintech/Spend mgmt platform (e.g. Payhawk) | FX from 0.30% above mid-market, plus a low transfer fee | Seconds to 2 hours on instant rails (Faster Payments, SEPA Instant); up to 2 business days on SEPA; up to 3–5 business days on ACH/SWIFT | Local + SEPA + SWIFT | Strong approvals, invoice-currency payment options, multi-entity, ERP sync |
| Multi-provider stack | Varies | Varies | Varies | Fragmented (no single audit trail) |
Bank vs fintech: Which option is best for your business?
When supplier payments span multiple currencies and entities, consolidation wins. A single system reduces reconciliation work, control gaps, and confusion.
Take Alma, for example. The finance team was switching between providers to reimburse employees and pay suppliers across currencies. This slowed approvals and reduced visibility.
They onboarded Payhawk to unify international spend management and payment software in a single platform. Now, the team saves time and money on cross-border payments. Speaking on the upgrade, Simon Shohet, Finance and Strategy Senior Manager at Alma, said:
Payhawk's international bank payments feature means we now have one platform to manage our payments, from employee reimbursements to paying suppliers across different currencies, including USD. We love that we don't have to switch between different providers to make payments and have a complete overview of spend in Payhawk.
What to look for in an international payment provider
Once you’ve chosen a payment system, the next task is choosing the best provider. Use this checklist to evaluate options.
Does the provider:
Hold balances in the currencies your company uses
- Yes
- No
Pay suppliers in the invoice currency without forced conversion (the real benefit: no double FX).
- Yes
- No
Let you choose rails per payment - Local, SEPA, SWIFT, or partner-led FX
- Yes
- No
Show FX, transfer, and intermediary fees clearly before approval
- Yes
- No
Release payments only after approval
- Yes
- No
Sync every payment to your ERP with invoice, approval trail, and status updates
- Yes
- No
Give AP, Treasury, and Finance one data dashboard across entities
- Yes
- No
Meet security and compliance needs (PCI DSS; safeguarded funds, sanctions screening)
- Yes
- No
If you answered “Yes” to all questions, you can treat the provider as a strong candidate for your shortlist.
See what hands-off accounts payable looks like

Best international payment systems for paying suppliers
Top solutions combine international supplier payments with other finance workflows. These include invoice processing, approvals, corporate cards, expense management, ERP integration, and multi-entity oversight.
We compared six international payment software platforms across five areas:
- Suitability for different business models
- International payment capabilities
- Approval and accounts payable controls
- ERP and accounting integrations
- What you should verify before purchasing
Payhawk
- Best for: Mid-market and multi-entity businesses that want to manage supplier payments, cards, expenses, approvals, entities, and finance data in one platform.
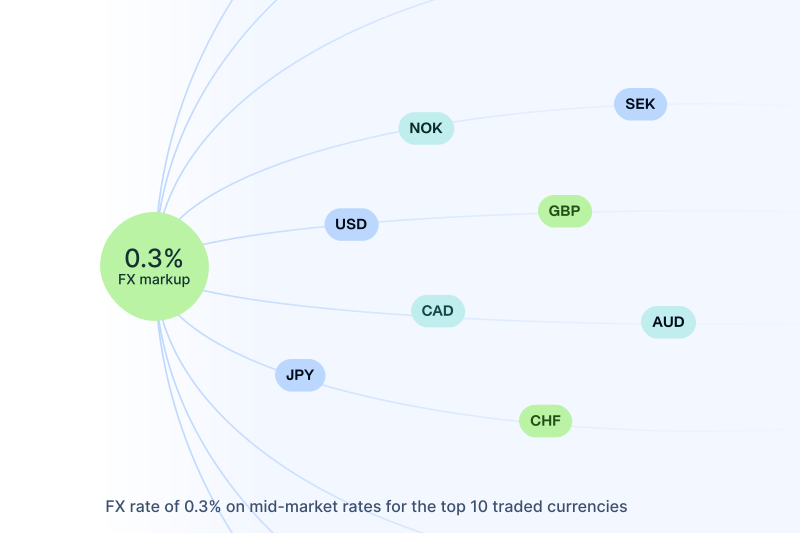
- International payments: Sends supplier payments in 115+ currencies to more than 150 countries, using both local and cross-border rails, with FX from 0.30% above the mid-market rate on the top 10 currencies (up to 0.95% on others) and no forced double conversion. Finance can follow each payment from submission to completion in one place.
- Approvals & AP controls: AI-backed Optical Character Recognition (OCR) invoice capture, customizable approval workflows, supplier payments, card controls, and role-based access, with a full audit trail, so finance teams can track each step of the AP process in one place.
- ERP & accounting integration: Connects directly to ERP and accounting systems such as NetSuite, Sage Intacct, and Xero, and automatically exports invoices, payments, and coding once they're reviewed, so ledgers stay accurate without manual entry.
- What to verify: Where Payhawk is available, which account and payment currencies it supports, how your main payment corridors price out, and what implementation and licensing look like for your entity structure.
Airwallex
- Best for: International businesses that want multi-currency accounts, cross-border supplier payments, and bill payments alongside cards and expense management.
- International payments: Multi-currency accounts, cross-border transfers, and local payment rails where available. Its Bill Pay product lets teams collect, approve, and pay supplier invoices in one place, and bills can be paid by card only if the vendor accepts cards.
- Approvals & AP controls: Bill Pay captures uploaded or emailed invoices with OCR, routes them through multi-layer approval workflows, and pays suppliers in multiple currencies, then syncs bill and payment data to your accounting system for reconciliation. Airwallex also offers corporate cards and expense management, with spend tracked and policies set centrally across multiple entities.
- ERP & accounting integration: Integrates with Xero, QuickBooks, and NetSuite, so teams can import bills, run approvals and payments, and sync data back to their ledgers.
- What to verify: Which features are available where your entities are registered, how approvals work for bills paid by transfer versus card, which plan includes the integrations and multi-entity features you need, and typical transfer times on your main payment corridors.
Spendesk
- Best for: European mid-market businesses that want spend control, corporate cards, accounts payable, international supplier payments, and multi-entity management in one platform.
- International payments: Spendesk pays suppliers through its partnership with Wise, with transfers to 71 countries in 31 currencies at the mid-market rate. As of October 2026, it lists a 0.5% FX fee plus a €4 transfer fee for major currencies such as USD on local rails. On a payment worth €3,000, that comes to €19, compared with about €10 on Payhawk (0.30% FX plus a €1 local-rails fee). For teams paying overseas suppliers often, that difference adds up.
- Approvals & AP controls: Captures invoices by upload or email, matches them against purchase orders and delivery notes, routes them to approvers by amount, and keeps an exportable audit trail. Full payment services are available for companies in the EEA, UK, and US; subsidiaries elsewhere can use the software without payment services.
- ERP & accounting integration: Direct integrations include NetSuite, Xero, DATEV, QuickBooks, and Sage 100, with CSV and XLS exports for other systems. Spendesk's NetSuite documentation lists some limits, including no SuiteTax support.
- What to verify: Which countries and currencies the Wise-powered transfers cover for your corridors and which fee tier applies, how wallet top-ups fit your cash management, and how the integration handles your ERP's tax and multi-entity setup.
Ramp
- Best for: US-headquartered businesses that want cards, expense management, bill pay, and accounting automation in one platform, with procurement available as an add-on.
- International payments: Ramp Bill Pay sends international payments in USD for most customers, and can pay suppliers in local currency in supported countries for customers on NetSuite, QuickBooks Online, Xero, or Sage Intacct. The exchange rate is set when the payment is initiated.
- Approvals & AP controls: Captures invoices, routes approvals, and tracks each bill through to payment. Purchase orders and two- and three-way matching come with Ramp's procurement add-on to Ramp Plus or Enterprise, and multi-entity requires Ramp Plus.
- ERP & accounting integration: Integrates with NetSuite, Sage Intacct, QuickBooks Online, and Xero, so finance can sync bills and payments instead of posting them by hand.
- What to verify: Which countries and currencies local-currency payouts cover with your ERP, the FX and transfer fees on your main corridors, and whether you need Ramp Plus and the procurement add-on for your approval and multi-entity setup.
Pleo
- Best for: European businesses that want corporate cards, expense management, and supplier invoice approval and payment in one tool.
- International payments: Upload supplier invoices, request approvals, and pay now or schedule payment for a set date. Pleo sends supplier payments via SEPA, Faster Payments, or wire transfer in 50+ currencies, and its multi-currency account holds EUR, GBP, USD, DKK, SEK, and NOK. FX fees on card and invoice payments range from 1.49% to 2.00% depending on plan, plus £6–£8 per international payment. Pleo's help center notes that US customers can't pay supplier invoices through Pleo.
- Approvals & AP controls: Pleo AP includes OCR invoice capture, duplicate detection, approval rules by amount, team, or custom tags, and payment scheduling. Invoice approval flows start on the Build plan. In multi-entity groups, admins switch between entities in the app.
- ERP & accounting integration: Integrates with Xero, QuickBooks Online, NetSuite (via a SuiteApp), and Sage Intacct, with Sage 50 supported through CSV export. In Xero, exported invoices appear as bills, and their approval and payment status updates automatically.
- What to verify: Whether Pleo supports supplier payments for your US and non-US entities, which currencies and destination countries it covers for your corridors, which plan includes the approval and multi-entity features you need, and how its ERP integration handles invoices, payments, and multiple entities.
Tipalti
- Best for: Businesses with high-volume or complex global AP that need supplier self-onboarding, tax-form collection, and payee compliance checks in one payables platform.
- International payments: Sends payments to 200+ countries and territories in 120+ local currencies, using 50+ payment methods including US ACH, global ACH, wire transfer, PayPal, and check. Payments are funded from Tipalti accounts, which must hold enough funds before payments are released.
- Approvals & AP controls: Covers supplier self-onboarding, OCR invoice capture, approval rules, and 2- and 3-way PO matching on higher-tier plans, plus tax-form collection, supplier data validation, sanctions screening, and payment-status notifications. The Tipalti Card is included in its Accounts Payable plan, while Procurement, Expenses, and Treasury are add-on modules.
- ERP & accounting integration: API integrations with NetSuite, Sage Intacct, Microsoft Dynamics 365 Business Central, Acumatica, QuickBooks Online, and Xero sync in near real time; other ERPs connect through file-based integrations that sync on a schedule or on demand.
- What to verify: The subscription tier you need, per-invoice and per-payment transaction fees, FX rates on cross-border payouts, which modules are add-ons, how your entities are funded, and whether your ERP uses an API or file-based integration.
How Payhawk supports international vendor payments
Payhawk combines global payments with a comprehensive spend management platform to make completing AP tasks efficient, cost-effective, and safe. For example, your team can:
- Pay in 115+ currencies and hold balances in currencies such as EUR, GBP, and USD to avoid double conversion and FX surprises
- Use the right payment rail for each transaction, with local rails where available, to move money without higher costs or multiple providers
- Release supplier payments and reimbursements after sign-off, to avoid unauthorized payments and maintain audit trails
- Provide Visa corporate cards with built-in spend controls to accelerate reconciliation and month-end close
- Automatically export reviewed card transactions to your ERP and accounting tools with integrations to reduce manual work and data errors
- Let Finance, AP, and Treasury see payments and audit trails across entities from one dashboard with Payhawk’s multi-entity management solution
- Offer PCI DSS Level 1 security, safeguarded funds, and role-based access to keep payments compliant and budgets safe
Common mistakes when choosing an international payment system
Without the right knowledge, mistakes can happen as your finance team tries to improve supplier payments. Let’s look at the most common ones.
| Problem | Why it happens | Fix |
|---|---|---|
| Choosing a system based on headline FX rate alone | Teams focus on the visible FX rate and ignore extra intermediary markup fees | Compare total cost, including FX, transfer, and intermediary fees |
| No approval process for payments | Payments move on habit or trust without requesting approval before release | Require approval before releasing payments to cut fraud and error risk |
| Forced source-currency conversion | The system only lets you pay from a home currency, so every invoice needs converting | Hold balances and pay in the invoice currency to avoid double FX conversions |
| No ERP sync | Payments sit in separate systems and spreadsheets until month end | Require automated ERP sync and a full audit trail |
| Running finance processes on disconnected providers | Different teams adopt different tools for card and bank payments | Consolidate payment options into one international payment system with unified control |
Is your international payment setup ready to scale?
Before making changes, assess where your current setup stands among international payment systems. Use this scorecard to see how ready your setup is for growth.
Instructions: Answer “Yes” or “No” to the following questions and total your “Yes” answers.
- Do all supplier payments run through one system?
- Can you hold and pay in your suppliers’ currencies?
- Are FX and fees visible before approval?
- Does every payment require approval before release?
- Does each payment sync to your ERP automatically?
- Can you see payments across entities in one place?
Scoring (“Yes” answers):
- 0-2: Your setup costs you money and control. Consolidate onto one system, fix any missing approval processes, and ERP sync to avoid costly errors
- 3-4: You have a solid base but have gaps. Tighten FX visibility and approvals. Merge more flows before scaling international vendor payments
- 5-6: Your platform is ready to scale internationally. Focus on improving policies, analytics, and team workflows
Choose a system that gives control, not just speed
The real differentiator for finance teams is control and quick, accurate reconciliation. Good international payment systems balance cost, speed, reconciliation, and control, not just cheap, fast transfers.
When Finance keeps approvals, FX visibility, clean data, and integrations at the center of its setup, your business stops leaking margin and time. From here, your company grows more profitably, strengthens cash flow planning and makes better decisions.
For a deeper dive into rails, FX, and strategy, download the ultimate guide to international payments. If you want to see how you can optimize your setup, explore how Payhawk’s international payment system works.
With over 15 years of experience in SaaS and digital communications, Paul specializes in translating complex financial concepts into clear, engaging narratives. At Payhawk, he combines creativity and analytical insight to help finance teams thrive through data-driven storytelling.
Related Articles


AI in accounts payable: what it automates and what humans verify

